The Heavy Burden of Unending Monthly Payments
You open your mortgage statement, expecting to see a nice dent in your balance. Instead, out of the $1,200 you sent, a measly 200 bucks actually went toward your loan. The rest? Poof. Gone to interest. It makes you feel like you are running on a treadmill that keeps speeding up while you are sweating your heart out. Let me show you exactly how the banking system is rigged, and more importantly, how you can finally hit the stop button and beat them at their own game.
The rest of my hard-earned money had completely vanished into thin air as an interest payment. I felt completely defeated and honestly, a little bit sick. I asked myself how I was ever going to pay off this massive debt when the bank was taking almost everything. It felt like I was running on a treadmill, sweating and working hard, but barely moving an inch forward.
But what if I told you that the bank's system has a specific mathematical rhythm? Once you figure out how this system works, you can completely turn the tables in your favor. You do not have to be a victim of endless interest charges anymore.
The Game Plan: Quick Takeaways
- The Bank Gets Paid First: Lenders front-load your loans, grabbing their profit before you even make a dent in your actual debt.
- The 13th Month Trick: Sending just one extra principal-only payment a year can wipe 4 to 5 years off a standard 30-year mortgage.
- Bi-Weekly Hacks: Splitting your payment in half every two weeks tricks the calendar into giving you a free extra payment every year without wrecking your budget.
- Watch Your Step: Always confirm with your bank that your extra cash is going straight to the 'principal'. Otherwise, they will just hold it for next month's regular bill!
Cracking the Code of Your Loan Statement
To beat the bank at their own game, we need to completely understand how they make their money. This entire system revolves around something called an amortization schedule. It sounds like a complex mathematical term, but it is actually very simple to grasp.
An amortization schedule is simply a detailed table that shows every single payment you will make for the entire life of your loan. It breaks down exactly how much of your monthly check goes to interest, and how much actually reduces your debt.
How Banks Secure Their Profits First
When you first get a loan, lenders use a specific formula to protect their own pockets. This practice is known as front-loading the interest. During the first few years of your loan, the bank takes their profit right off the top.
If you look at your payment table for month one, you will see a massive portion assigned to interest. The principal portion, which is the actual money you borrowed, receives only a tiny fraction of your payment.
This is why you can pay a mortgage for five years and still owe almost the exact same amount you originally borrowed. The lender makes sure they get their profit long before you gain any real ownership of your home or car. Understanding this setup is the very first step toward taking your financial power back.
Pro Tip: When I first realized how much interest I was paying in year one, I immediately called my lender to ask for a printed copy of my full payment schedule. Keeping that physical paper on my desk made me so angry that it motivated me to find extra cash to throw at the principal every single month!
The Seesaw Effect of Loan Repayments
Think of your monthly payment like a playground seesaw. On one side, you have the interest, and on the other side, you have the principal. For a fixed-rate loan, your total monthly payment amount never changes.
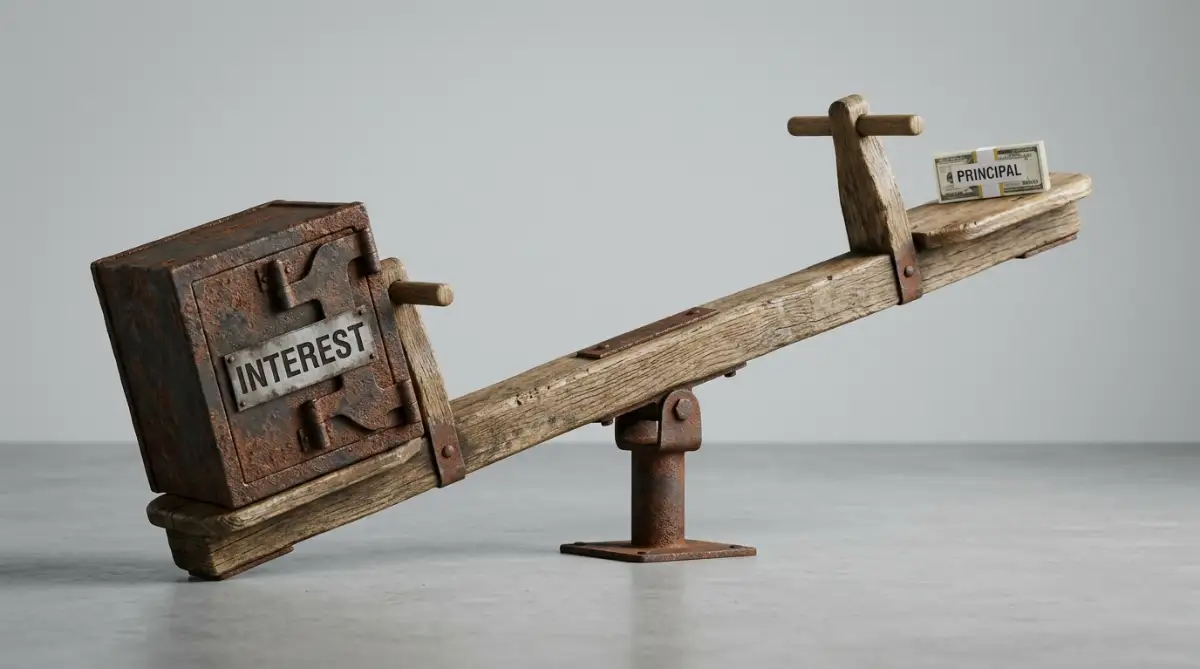
However, the balance on that seesaw shifts slightly every single month. As your total debt slowly drops, the amount of interest the bank can legally charge you also drops. Because the interest goes down a tiny bit, the principal portion goes up a tiny bit to keep the total payment the same.
Eventually, usually halfway through the loan term, the seesaw finally tips in your favor. You start paying more toward the principal than you do toward the interest. Our goal is to force that seesaw to tip in your favor much earlier than the bank planned.
Smart Tactics to Force Your Balance Down Early
Now that you know how the system is rigged, it is time to fight back. You do not need to win the lottery to pay off your debt early. Small, consistent actions can shave years off your repayment timeline.
The "One Extra Payment" Secret
One of the most popular and simple ways to crush debt is making just one extra payment per year. If your monthly bill is $1,000, you simply aim to pay $13,000 over the course of twelve months instead of $12,000.
Because that extra $1,000 does not have any regular interest attached to it for that specific month, the entire amount goes directly toward your principal balance. This instantly lowers the balance that your future interest is calculated on.
Over a standard 30-year term, making just one extra payment a year can easily cut off four to five years of payments.
Myth vs Math: The Real Cost of Minimum Payments
Here is exactly what this looks like in real life on a $300,000 mortgage at a 6% rate:
| Payment Strategy | Monthly Bill | Total Interest Paid | Years to Pay Off |
| :--- | :--- | :--- | :--- |
| Standard (12/yr) | $1,798 | $347,500 | 30 Years |
| +1 Payment (13/yr) | $1,798 (+1 extra) | $270,000 | 24 Years |
Boom. You just saved over $77,000 and bought back 6 years of your life without doing any crazy math.
Before you start sending extra money, you need to make sure you are doing it the right way! Watch this quick guide to avoid the most common debt payoff mistake.
Breaking the Calendar: Bi-Weekly Payments
If coming up with a full extra payment at once feels too heavy, try the bi-weekly method. Instead of paying your bill once a month, you split your normal payment exactly in half. You then send that half-payment to the lender every two weeks.
Because there are 52 weeks in a year, you will end up making 26 half-payments. This naturally equals 13 full payments over the course of the year.
You will not even feel the pinch in your budget because you are just aligning your bills with your paychecks. Here is a simple look at how this changes your strategy:
Rounding Up Your Monthly Bill
Sometimes the best strategies are the ones you barely notice. Let us say your monthly auto loan payment is $342. Try setting your automatic bank transfer to a flat $400 instead.
That extra $58 might just feel like a skipped dinner at a restaurant to you. But to your loan balance, it is a powerful weapon. Every single extra dollar you send automatically chips away at the core debt.
This method works incredibly well because it requires zero ongoing effort. You set it up in your banking app once, and you simply forget about it while your debt shrinks faster in the background.
Myth vs Reality: How Extra Money is Applied
A lot of people think that simply sending extra money will automatically solve their problems. Sadly, banks can be quite tricky with how they handle extra cash.
Myth: Any extra money I send is automatically used to reduce my main balance.
Reality: Many lenders will take your extra money and simply apply it to your next regular monthly bill.
This means they basically hold your money in advance and still charge you the regular interest rate. You must explicitly tell your lender that the extra money is a "Principal-Only Payment."
You can usually select this specific option in your online portal when making a manual transfer. If you do not see the option, you need to call your bank and have them set up a strict rule for your account.
Using Windfalls for Principal-Only Drops
Throughout the year, most of us run into unexpected chunks of cash. This could be a tax refund, a work bonus, or even money from selling old furniture.
Instead of treating this money as fun cash, use it as a targeted strike against your loan balance. Dropping a sudden $2,000 payment directly onto your principal creates a massive shift in your amortization schedule.
Because interest is calculated based on your daily or monthly remaining balance, a sudden drop permanently lowers the interest you will owe for every single month going forward. You essentially buy yourself out of future interest charges.
Why Mortgages and Auto Loans Behave Differently
While the math of amortization applies to almost all installment loans, the daily mechanics can differ. Mortgages typically calculate interest on a strict monthly basis. Auto loans, on the other hand, often use a simple daily interest formula.
With a daily interest auto loan, the specific day you make your payment actually matters. If you pay your car bill a few days early, fewer days of interest have built up.
This means a slightly larger portion of your regular payment will slide over to the principal side. By simply moving your payment date earlier in the month, you can naturally speed up your payoff journey without spending an extra dime.
Finding the Magic Tipping Point
If you print out your payment table, you can grab a highlighter and look for the magic tipping point. This is the exact month where the principal portion finally becomes larger than the interest portion.
For a long-term loan, this might be at month 180. Every time you make an extra principal payment, you drag that tipping point closer to the present day.
Seeing that highlighted row move closer and closer is an incredible psychological boost. It turns a boring financial chore into a highly rewarding game where you are constantly beating the bank.
Common Mistakes to Avoid on Your Journey
While attacking your debt is a great goal, you have to protect yourself along the way. The biggest mistake people make is draining their entire emergency savings just to make an extra principal payment.
If your car breaks down tomorrow and you have zero cash, you will probably put the repair on a high-interest credit card. You just traded a low-interest debt for a much worse high-interest problem.
Always keep a safe cash buffer in your bank account before you start aggressively paying down your loans. Your financial safety net is just as important as your debt payoff speed.
Another mistake is attacking the wrong debt first. If you have a credit card charging 22% interest, you should not be sending extra money to a mortgage that only charges 4%. Always target the debt that is draining your wealth the fastest.
Quick Pro-Tip I always share: Do not guess which debt is bleeding you the most. Use the 'Avalanche Method'. List all your debts on a piece of paper right now and sort them purely by the interest rate, from highest to lowest. Ignore the total balances for a minute. You attack that top number with everything you have, while just paying the bare minimum on the rest. It is the absolute fastest mathematical way out of the hole.
Next-Level Strategies to Crush Your Loan Balance
Once you understand the basic math behind your monthly payments, you can start using some truly powerful strategies. These are the exact methods financial experts use to save thousands of dollars on interest. You do not have to be a math genius to apply them to your own life.
One of the best-kept secrets in the banking world is a process called mortgage recasting. A lot of people assume that the only way to lower their monthly bill is by completely replacing their loan. They spend hours reading about how do mortgage rates work just to decide if they should refinance.
But refinancing resets your payment clock right back to month one. This means you start paying that massive front-loaded interest all over again. Recasting is entirely different and much safer for your long-term wealth.
When you recast, you drop a large lump sum of money directly onto your principal balance. The bank then recalculates your monthly payment based on that new, much smaller balance. Your interest rate stays exactly the same, and your original payoff date does not change.
This is incredibly helpful for people who just sold a property or received an inheritance. If you are exploring self-employed home refinancing just to get a cheaper monthly bill, ask your bank about recasting first. It usually only costs a small administrative fee and saves you from paying massive closing costs.
The Power of Micro-Payments on Daily Interest
If you have a daily interest loan, like most standard car notes, changing your payment frequency can create magic. Every single day you hold the borrowed money, a tiny amount of interest is added to your account.
Instead of making one large payment at the end of the month, try making weekly micro-payments. If your bill is $400 a month, set up an automatic transfer of $100 every single Friday.
Because you are giving the bank money earlier in the billing cycle, the daily interest does not have time to grow. According to the Consumer Financial Protection Bureau guidelines on loan applications, this naturally forces more of your money toward the core debt.
It sounds like a tiny change, but over a five-year term, those saved daily pennies turn into hundreds of dollars. You also never have to worry about missing a massive payment at the end of the month.
Automate Your Salary Increases
We all love getting a raise or a bonus at work. Our natural instinct is to immediately upgrade our lifestyle and start spending more. But if you want to become completely debt-free, you need to trick your own brain.
Whenever your salary increases by a certain percentage, increase your automatic debt payment by that exact same amount. If you get a 5% raise at work, bump up your extra principal payment by 5%.
You will never miss the money because you never got used to spending it in the first place. This simple behavioral shift is a proven way to build wealth without feeling restricted. In fact, research from the National Bureau of Economic Research shows that automating good financial decisions is the most reliable way families escape debt.
You can apply this exact same logic when you are managing unsecured loans without credit damage. By simply redirecting new income toward old debt, you accelerate your payoff schedule massively.
Dangerous Traps That Keep You in Debt Longer
While attacking your balance is an amazing goal, the road is full of hidden traps. Banks are very smart, and they have systems designed to keep you paying interest for as long as legally possible.
I have seen so many hard-working people make small mistakes that completely ruin their early payoff plans. Let us walk through the most common pitfalls so you can protect your hard-earned money.
The "Advance Payment" Illusion
This is easily the most heartbreaking mistake people make when trying to get ahead. Imagine you work overtime all weekend just to send an extra $500 to your auto lender. You feel amazing because you think you just knocked $500 off your core debt.
A month later, you log into your account and see that your overall balance barely dropped at all. Instead, your dashboard says, "Next payment not due for two months."
The bank did not apply your $500 to the principal. They simply took your cash, held it in a separate account, and used it to pre-pay your next regular bill. This means they are still actively charging you the exact same amount of interest!
If you do not strictly check the "Principal Only" box, your early debt payoff strategy might actually cost you more in lost opportunity. Always verify how your specific lender processes extra funds by reading their terms or calling customer service.
Refinancing the Clock Away
It is incredibly tempting to refinance when interest rates drop. You see advertisements promising a lower monthly payment, and it feels like an easy win.
However, when you refinance a loan you have had for a few years, you are starting the amortization schedule all over again. You go right back to the phase where the bank takes all their profit upfront.
You might save $100 a month on your actual bill, but you will likely pay thousands more in interest over the new life of the loan. This is why debunking common myths about debt consolidation loans and credit scores is so important before signing any new paperwork.
Before you agree to start over, sit down with a calculator and look at your current payment table. Often, you will find that just keeping your current loan and sending extra cash is a much smarter move.
Draining Your Emergency Safety Net
There is a powerful psychological rush that comes with watching your debt numbers go down. Some people get so addicted to this feeling that they throw every single spare dollar at their loans.
They empty their savings accounts just to hit a specific payoff milestone. But life is incredibly unpredictable, and emergencies do not care about your debt-free goals.
If your car breaks down or you lose your job, you will suddenly find yourself with zero cash. This is exactly how people end up panicked, wondering what to do when they cannot pay your auto loan this month.
Without cash reserves, you will be forced to rely on high-interest credit cards to survive. You just traded a structured, low-interest problem for a chaotic, expensive emergency. According to the Federal Deposit Insurance Corporation (FDIC), keeping a liquid savings account is the foundation of safely paying down larger debts.
Your Roadmap to Becoming Completely Debt-Free
You now have a deep understanding of how the banking system actually operates. You can clearly see how the math is stacked against you in the early years, and exactly how to flip the script.
The secret is not making a massive, impossible lump-sum payment. The real secret is consistency and understanding exactly where your money is going every single month. By forcing extra dollars directly onto your principal, you are quite literally buying back your own freedom.
If your interest rate is painfully high, you can always try to negotiate a lower interest rate on a mortgage or auto loan first. Once you secure a fair rate, use every single tactic we discussed to aggressively attack the core balance.
Set up those automated micro-payments, round up your monthly bills, and explicitly tell the bank where to put your extra money. These small daily choices will eventually create a massive snowball effect that wipes out your debt years ahead of schedule.
A Word From My Own Journey
I know firsthand how exhausting it feels to stare at a mountain of debt that refuses to shrink. My own journey to becoming debt-free felt completely impossible during those first few heavily front-loaded years.
But I promise you, the day I made that final principal-only payment and saw my balance hit absolute zero was the best feeling in the world. You have the exact same power to take control of your financial future starting right now. Stay patient, trust the math, and keep chipping away at that principal balance every single chance you get!
Common Questions About Beating The Amortization System
Does paying extra to principal reduce my monthly payments?
No, making extra principal payments will not lower your fixed monthly bill. Instead, it shortens the total length of your loan and significantly reduces the total interest you will pay overall. If you specifically want to lower your monthly bill, you would need to ask your lender about recasting the loan.
Can I ask my bank to change my amortization schedule?
You cannot directly ask a bank to rewrite the standard mathematical formula of your original loan. However, every time you make a verified principal-only payment, you automatically alter the schedule yourself. You force the balance down, which permanently changes how future interest is calculated.
Is it better to save my extra money or pay off my principal early?
This completely depends on your loan's interest rate compared to what you can earn in a savings account. If your loan charges 7% interest but your savings account only pays 4%, it is mathematically smarter to pay off the debt. Just make sure you always keep a fully funded emergency cash reserve untouched.
How do I make sure my extra payment actually goes to the principal?
You must explicitly instruct your lender how to apply the funds before you send the money. If you are paying online, look for a specific drop-down menu or checkbox labeled "Apply to Principal Only." If you are mailing a check, write "Principal Only" clearly in the memo line and include a sticky note with instructions.
Why is my first year of payments mostly just interest?
Lenders use a heavily front-loaded math formula to protect their financial interests early on. Because your starting balance is at its absolute highest in month one, the daily interest charge is also at its peak. As you slowly pay down that massive core balance, the interest portion will gradually shrink over time.
Disclaimer: The information provided in this article is for educational and informational purposes only and does not constitute professional financial advice. Everyone's financial situation is unique. Please consult with a certified financial advisor or your specific lending institution before making major financial decisions or significantly altering your loan repayment strategy.