Waking Up to the Nightmare of a Missed Car Payment
So, your car payment is due, and your bank account is practically empty. Take a deep breath—I know exactly how suffocating that panic feels, but losing sleep will not fix it. You have a lot more power right now than you think, and I am going to show you exactly how to keep your car safe in your driveway this month.
This specific money problem is incredibly common, yet nobody ever wants to talk about it openly. When you cannot make your auto loan payment, the mental toll is heavy and immediate.
The heavy weight of financial fear changes your daily routine. Every time your phone rings with an unknown number, your heart jumps into your throat because you think it is a debt collector. You start driving extra carefully, almost paranoid that someone is following you to take your car back.
But I want you to take a deep breath right now. This is just a math problem, and every math problem has a logical solution if you take the right steps.
Quick Action Guide (Read This First):
- Call your lender before you hit the 30-day late mark to protect your credit score.
- Ask specifically for a "hardship deferment" to push your missed payment to the end of your loan.
- Check your loan contract right now—you likely have a 7 to 15-day hidden grace period.
- Never try to hide your car; the bank will hit you with massive private investigator fees.
Your Immediate Action Plan to Save Your Vehicle
When you find yourself short on cash for your auto loan, your brain naturally wants to hide from the problem. We think that if we just ignore the phone calls, maybe the bank will forget about us. But hiding is the absolute worst thing you can do right now.
Instead of freezing up in fear, we need to take control of the situation. Lenders deal with financial hardships every single day. They have specific systems in place to help you, but they can only help if you reach out and ask for it.
Let us look at the exact steps you need to take right now to protect your car, your credit, and your mental peace.
Face the Fear and Call Your Lender Immediately
The very first thing you need to do is pick up the phone and call your bank or credit union. I know this sounds incredibly intimidating, but it is the most powerful move you can make.
When you call, you completely change the dynamic. You are no longer someone hiding from a debt. You are a responsible adult proactively trying to find a solution.
Ask to speak to the hardship department or the loss mitigation team. These representatives are specifically trained to help people who are going through temporary money troubles. Be totally honest with them about why you are short on cash this month.
Whether you lost your job, had a medical emergency, or had to pay for a massive home repair, tell them the truth. The more details they have, the better they can match you with a helpful program.
Steal My Quick Hardship Script:
Not sure what to say when the bank picks up? Just read this:
"Hi, my account number is [Your Number]. I recently had an unexpected emergency and I cannot make my full payment this month. I want to keep my account in good standing. What deferment or forbearance options do you have for me today?"
Myth vs. Reality About Auto Lenders
- The Myth: The bank desperately wants to steal your car and sell it to someone else.
- The Reality: The bank just wants their money. Repossessing a car is incredibly expensive and annoying for lenders. They lose money on tow trucks, auction fees, and paperwork. They would much rather work out a deal with you.
The Real-Life Repossession Timeline:
- Day 1 to 15 Late: You are in the grace period. You get to keep the car, but late fees might kick in.
- Day 30 Late: Your credit score takes a major hit.
- Day 60 to 90 Late: The bank officially assigns a repo agent. (Note: In strict places like Texas or Florida, they can legally tow your car the very day after you miss a payment!)
Ask About the Hidden Grace Period
Before you panic about extra fees, you need to know about your grace period. Almost every standard auto loan comes with a built-in grace period for late payments.
This means you usually have anywhere from seven to fifteen days after your official due date to make the payment without getting a late fee. More importantly, your payment is usually not reported to the credit bureaus as late until it is a full 30 days past due.
Check your original loan contract or look on your online portal to see exactly how many days you have. If you just need a little extra time until your next paycheck arrives, this grace period might be your easiest solution.
However, you should still call the lender to let them know the payment will be a few days late. This simple communication stops them from sending automated warning letters to your house.
Request a Formal Hardship Deferment
If your money problems are going to last longer than a few days, you need to ask your lender for a deferment. A deferment is a special agreement where the bank lets you skip one or two monthly payments entirely.
They do not just forgive the debt, of course. They take those skipped payments and add them to the very end of your loan term. So, if your loan was supposed to end in December, it will now end in January or February.
This gives you a massive breathing room right now when you need it most. You get to keep driving your car, your credit score stays safe, and you do not have to stress about the money this month.
Just keep in mind that interest will usually continue to grow during these skipped months. You will end up paying a little bit more overall, but it is a small price to pay to keep your car safely in your driveway.
Pro Tip: When I tried to handle my own late payment issue, I made the mistake of waiting until I was already 15 days late before calling my bank. I learned the hard way that lenders are much more willing to give you a deferment if you call them before your actual due date. Always try to be proactive rather than reactive with your bank.
Watch this quick video to understand exactly what to say to your bank to get your payment deferred without ruining your credit.
Explore the Option of Loan Forbearance
Sometimes, your lender might offer forbearance instead of a deferment. While they sound very similar, they work a little differently behind the scenes.
With a deferment, your payments are moved to the end of the loan. With a forbearance, the lender might allow you to make a reduced payment or pause payments for a set period. However, once the forbearance period ends, you might have to pay the missed amount as a lump sum or agree to a higher monthly payment to catch up.
It is highly recommended that you ask the customer service agent to explain exactly how you will have to repay the paused amount. You do not want to be surprised by a massive bill three months from now.
Consider Refinancing for a Permanent Fix
If you find yourself struggling to make your car payment every single month, a temporary pause will not fix the root issue. Your monthly bill is simply too high for your current income.
In this scenario, you should seriously look into refinancing your auto loan. Refinancing means you take out a brand-new loan to pay off the old one. The goal is to get a new loan with a longer repayment term or a much lower interest rate.
For example, let us say your current payment is $500 a month because you took out a three-year loan. By refinancing to a five-year loan, you stretch out the balance over more time. This could easily drop your monthly bill down to $300 a month.
Yes, you will be in debt for a longer period. But having a payment you can actually afford is much better than risking repossession every 30 days. You can always check rates with local credit unions, as they often have the most friendly terms for community members.
Creative Ways to Generate Quick Cash
Sometimes the bank simply says no. If your credit score has recently dropped, or if you have already used a deferment this year, the lender might not offer any assistance.
When this happens, you have to get creative and aggressive about finding the cash quickly. Look around your house for items you no longer use. Electronics, video game consoles, designer clothes, or old furniture can be sold locally within 24 hours.
You can also look for immediate gig work. Delivering food, walking dogs, or helping people move furniture on the weekend can quickly generate a few hundred dollars.
It might feel exhausting to work extra hours when you are already stressed. But remember, this is a short-term sprint to save your vehicle and protect your credit history. You only need to hustle this hard until the payment is made.
Adjusting Your Budget to Stop the Cycle
Once you survive this month's crisis, you need to make sure this never happens again. Living paycheck to paycheck with zero margin for error is a terrifying way to live.
Sit down with a pen and paper and track exactly where your money went over the last 30 days. You will probably be shocked by how much money leaked out through fast food, forgotten subscriptions, or impulse online shopping.
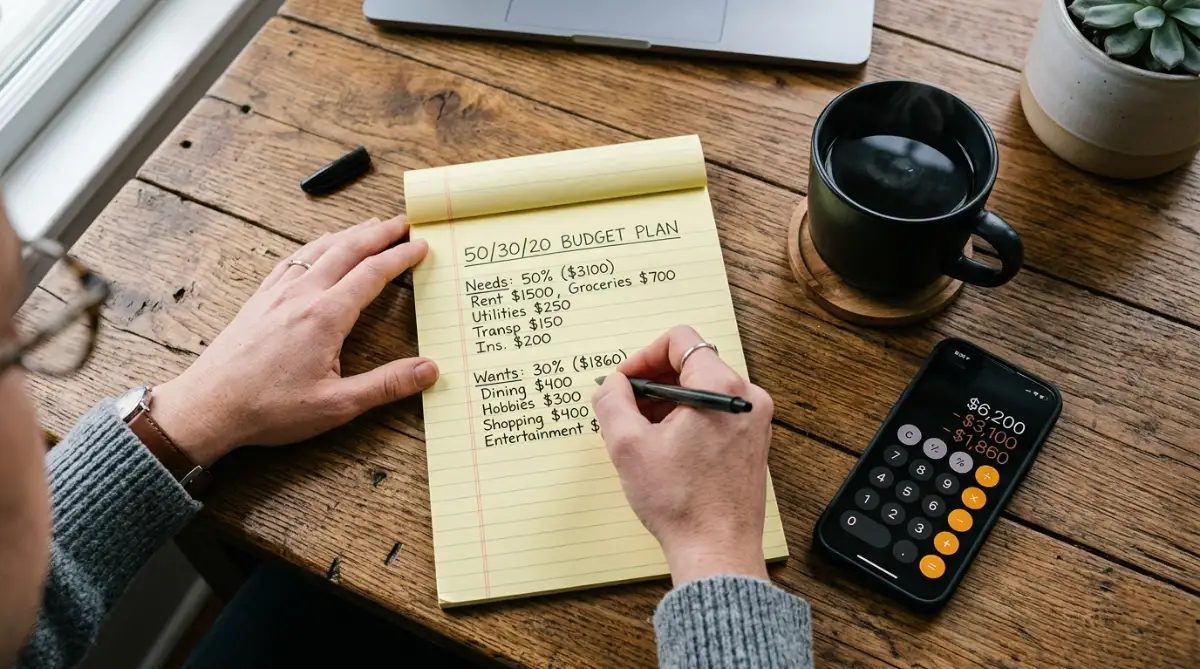
You need to actively tell your money where to go instead of wondering where it went. Start using a simple budgeting method, like the 50/30/20 rule. This means 50% of your income goes to needs like your car payment and rent.
Then, 30% goes to wants, and 20% goes straight into savings or paying off debt. By forcing yourself to build a small emergency fund, you create a soft safety net. The next time you are short on cash, you can just pull from your savings instead of panicking.
Voluntary Surrender: The Absolute Last Resort
We need to talk about the absolute worst-case scenario. What if you lost your job entirely, you have zero income, and you know for a fact you cannot afford this car anymore?
In this situation, you might have to consider a voluntary surrender. This is when you willingly drive the car back to the dealership or the bank and hand them the keys. You are officially telling them you cannot pay the loan.
This will absolutely damage your credit score, just like a forced repossession would. However, it is slightly better because you avoid paying the expensive towing and storage fees that come with a forced repossession.
It also saves you from the public embarrassment of having a tow truck back into your driveway in front of your neighbors. A voluntary surrender is painful, but sometimes stepping away from an impossible debt is the only way to start rebuilding your financial life.
Taking quick action is the secret to surviving a missed car payment. You have options, you have rights, and you have the ability to fix this. Do not let fear paralyze you. Pick up the phone, make that difficult call to your lender, and start taking your power back today.
Strategic Moves to Secure Your Vehicle Long-Term
Surviving your immediate cash crisis is a huge victory, but we cannot stop there. The goal is to make sure you never have to experience this terrifying level of financial stress again. You need a solid, permanent plan to keep your car safely in your possession.
When you are constantly worried about missing payments, you cannot focus on enjoying your life. That is why we must shift our focus from temporary survival to long-term stability. The secret lies in taking proactive steps before the next billing cycle even begins.
Let us explore some highly effective strategies that financial experts use to protect their assets. These methods will help you build a strong safety net around your auto loan.
Master the Art of Split Payments
Most people wait until the end of the month to send one massive payment to their auto lender. If your paycheck is delayed by just one day, you instantly fall behind. This old method creates unnecessary anxiety and puts you at risk of late fees.
Instead, you should set up automatic bi-weekly payments. By sending half of your car payment every two weeks, you align your bills directly with your payday. This simple change completely removes the stress of scraping together a huge lump sum at the end of the month.
As a massive bonus, making bi-weekly payments actually reduces the total interest you pay over time. Because you are paying the principal down slightly faster, the bank cannot charge you as much interest. You will pay off your car faster without even noticing the extra effort.
Create a Dedicated "Car Emergency" Fund
You probably already know that you need a general emergency fund, but that idea is often too vague. When an emergency happens, we tend to drain our general savings for random things like a broken television. To protect your vehicle, you need a highly specific, dedicated savings account.
Open a completely separate, free checking account that is only used for car-related expenses. Every time you get paid, automatically transfer just twenty or thirty dollars into this hidden account. You must pretend this money does not exist for your regular daily spending.
When you suddenly have a flat tire, or if your hours get cut at work, you will not panic. You simply transfer the money from your dedicated car fund to cover the monthly bill. This tiny habit creates a powerful emotional shield between you and the repossession agent.
Restructure Your Total Debt Profile
Sometimes the car payment itself is not the actual problem. You might be struggling to pay your auto loan because your credit cards or personal loans are eating up all your cash. If you can lower your other monthly bills, your car payment will suddenly feel much more affordable.
You should take a hard look at your total monthly obligations. It might be time to read up on debunking common myths about debt consolidation loans and credit scores to see if combining your debts makes sense. Moving high-interest credit card debt to a lower-interest personal loan can free up hundreds of dollars in your monthly budget.
Before applying for new credit, you have to be very careful about your current credit score. The last thing you want is a hard inquiry that ends in a denial. Make sure you understand the silent reasons your personal loan application gets rejected every time so you can prepare properly.
Monitor Your Credit Like a Hawk
Your credit report is essentially your financial report card, and your auto lender checks it constantly. If they see that you are falling behind on other bills, they might become less willing to offer you a hardship program. You need to know exactly what the bank sees when they look at your file.
Set up free credit monitoring alerts on your phone today. You want an instant notification if anything negative is reported, especially regarding how late payments impact your credit score. Catching a reporting error early can save you from being denied a helpful loan deferment later on.
If your credit is already heavily damaged, do not lose hope. There are still safe ways to access emergency funds. You just need to know how to get unsecured loans with bad credit safely without falling into predatory traps.
Negotiate a Permanent Loan Modification
If your income has permanently dropped due to a career change or illness, a temporary pause will not save you. You need to speak with the loss mitigation department about a permanent loan modification. This is very different from a simple deferment.
A modification literally changes the original terms of your contract. The bank might agree to permanently lower your interest rate, or they might stretch a four-year loan into a six-year loan. The goal is to drop your monthly payment to a number you can comfortably afford forever.
You will have to provide solid proof of your income drop, like recent pay stubs or a termination letter. The bank will review your file to see if a modification makes financial sense for them. Always remember that learning understanding how auto loans work directly from official sources like the Consumer Financial Protection Bureau will give you incredible negotiating power.
Dangerous Money Traps That Will Cost You Your Vehicle
When fear takes over, smart people start making incredibly terrible financial decisions. The sheer panic of losing your only mode of transportation can push you into a corner. We become desperate, and desperation is the easiest way to ruin your financial future.
I have seen so many people try to aggressively fix a missed payment, only to create a nightmare that lasts for years. You must protect yourself from these common, highly destructive mistakes.
Let us break down the absolute worst things you can do right now, and exactly why you need to avoid them at all costs.
The Toxic Payday Loan Cycle
The Scenario: Your car payment is late, and the bank is calling every single day. You see a bright neon sign for a payday loan store offering instant cash with no credit check. You borrow five hundred dollars to pay the car note, feeling totally relieved that the bank stopped calling.
The Hidden Danger: You just traded a very manageable problem for an absolute financial disaster. Payday loans often come with interest rates that equal three hundred or even four hundred percent a year. When your next paycheck arrives, the payday lender will take almost all of it to cover their insane fees.
Now you have no money left for groceries, rent, or next month's car payment. You will have to take out a second payday loan just to survive the week. This vicious cycle destroys families and almost always ends in a vehicle repossession anyway.
If you are a freelancer or side-hustler needing quick cash, look into easy collateral free business loans the step by step guide instead of toxic payday lenders. Traditional, regulated lending is always safer than predatory street corner loans.
Playing Hide-and-Seek with the Repo Agent
The Scenario: You get a final warning letter in the mail stating your car is scheduled for repossession. In a panic, you drive the car to your cousin's house across town and park it deep inside their closed garage. You think that if the tow truck cannot find the car, you get to keep it for free.
The Hidden Danger: You are now crossing the line from a simple civil contract dispute into potential criminal activity. Purposely hiding a vehicle with a lien on it can be considered defrauding a secured creditor. You are not outsmarting the bank; you are just making them incredibly angry.
The bank will simply hire a skip tracer, which is essentially a private investigator who tracks down hidden assets. They will check your family's addresses, your workplace, and even scan license plates at local grocery stores. When they finally find the car, they will charge you thousands of dollars extra for the massive investigation fees.
You should strongly educate yourself on the legal rules of vehicle repossession in your specific state. Knowing your actual legal rights is a thousand times better than hiding your car in the dark.
Ignoring the Debt Collection Letters
The Scenario: Your mailbox is full of thick, official-looking envelopes from your lender. Because you do not have the money to pay them, you simply throw the letters into the trash without even opening them. You convince yourself that ignoring the problem will make it disappear.
The Hidden Danger: Silence is the absolute worst message you can send to a bank. When you stop communicating, the bank assumes you have abandoned the vehicle or intend to steal it. They will immediately escalate your account from a "late payment" to a "high-risk recovery" status.
Opening those letters might reveal that they are actually offering you a settlement or a hardship program. Sometimes, they just want you to sign a form to pause your payments. By throwing the mail away, you might be throwing away your only lifeline.
If the bank sells your debt to a third-party agency, your situation gets even worse. You need to know your rights regarding aggressive debt collectors by reading the official guidelines on debt collection provided by the Federal Trade Commission.
Trading in a Heavily Upside-Down Car
The Scenario: You realize your monthly payment is way too high, so you drive to a local dealership to trade your expensive car for a cheap used one. You owe twenty thousand dollars on your current loan, but the dealer says your car is only worth ten thousand. They tell you not to worry, they will just roll the difference into the new loan.
The Hidden Danger: You just created a ticking financial time bomb called negative equity. You are now financing a ten-thousand-dollar used car with a twenty-thousand-dollar loan attached to it. Your new monthly payment might actually be higher than your old one, completely defeating the purpose of the trade.
If you ever get into a car accident and total this new vehicle, the insurance company will only pay what the cheap car is worth. You will instantly owe the bank ten thousand dollars out of your own pocket. Never roll massive negative equity into a new loan just to escape a temporary missed payment.
Your Personal Action Plan for Tomorrow Morning
You now have a complete, highly practical roadmap to save your vehicle. Reading this information was your first major victory, but your real success depends on what you do tomorrow morning. The stress you are feeling right now will only fade away once you take direct, confident action.
Do not let the fear of a difficult phone call cost you your primary mode of transportation. The bank representatives are just normal people sitting in a cubicle, and their main job is to help you figure this out. They want you to keep the car just as much as you want to keep it.
Start by writing down your exact monthly income and every single expense on a blank piece of paper. Call your lender first thing in the morning and politely ask for the loss mitigation department. Be honest, be proactive, and remember that this difficult season is only temporary.
I remember the exact moment I finally paid off my stressful car loan; the relief was absolutely incredible. I want you to experience that exact same freedom, and it starts by taking control of your current situation today!
Direct Answers to Your Biggest Car Payment Worries
How many car payments can you actually miss before repossession happens?
Most lenders will start the repossession process after your payment is 60 to 90 days past due. However, in some strict states, a bank legally has the right to repossess your vehicle the very day after a missed payment. You should never rely on a specific timeline; call your bank immediately to pause the clock.
Can I negotiate a lower payoff amount to keep my vehicle?
If your car is severely underwater and you are facing bankruptcy, some lenders will agree to a settlement for less than you owe. This will severely damage your credit score, but it clears the debt entirely. You usually need a large lump sum of cash on hand to negotiate this type of deal successfully.
Will handing the keys back stop them from charging me more money?
A voluntary surrender stops the expensive towing fees, but it does not erase your legal debt. If the bank auctions your car for less than your loan balance, they will still send you a bill for the remaining difference, known as a deficiency balance. You are legally required to pay that remaining balance even though you no longer have the car.
What is the fastest way to get a hardship deferment approved?
The absolute fastest method is to call your lender directly before your official due date arrives. Have your recent pay stubs and a very clear explanation of your current financial crisis ready to email them while you are on the phone. Proactive communication almost always guarantees a faster approval process.
Does a car loan deferment hurt my credit score immediately?
If you request and get approved for a deferment before your payment is 30 days late, it will not hurt your credit score at all. The bank will report your account as "current" or "paying as agreed" during the paused months. However, if you wait until you are heavily past due to ask for help, the late marks will remain on your credit report.
Disclaimer: The information provided in this article is for educational and informational purposes only and should not be considered professional financial or legal advice. Every individual's financial situation is entirely unique. Please consult with a certified financial planner, a legal professional, or your specific auto lender before making any major decisions regarding your personal loans or credit profile.