The Silent Heartbreak of a Denied Dream Home
Getting a home loan approved shouldn't feel like a top-secret FBI investigation, but it often does. You pay your bills on time, keep an eye on your credit score, and think you're totally ready to buy a house. Then, right out of nowhere, you get hit with a denial letter just days before closing. Let's talk openly about why underwriters flag certain things and how you can beat them at their own game.
I honestly thought my credit score was perfect, making me an easy candidate for a standard home loan. Yet, the underwriter found something in my file that I did not even know existed. That single moment made me feel entirely defeated and lost.
I had already started buying furniture in my head and planning which bedroom would belong to my son. Having to call my family and tell them that we were not moving after all was one of the hardest conversations of my life.
This is a quiet nightmare that happens to thousands of hardworking people every single day. You do everything right, follow the basic advice of your local bank, and still get hit with a sudden denial right before closing.
The stress of waiting for an underwriter to review your life is enough to make anyone lose sleep. Every time the phone rings, your stomach ties itself into tight knots wondering if they found a new problem.
Before We Start: 4 Rules to Keep Your Loan Safe
- Freeze your spending: Do not buy furniture, cars, or appliances on credit until you have the house keys in your hand.
- Keep your cash boring: Leave your savings alone. Do not move large amounts of money back and forth between accounts.
- Track every single dollar: If you sell something or receive a cash gift, you need a solid paper trail to prove where it came from.
- Say no to co-signing: Do not put your name on a loan or lease for anyone else, no matter how close you are.
Decoding the Mind of the Person Approving Your Loan
To stop this from happening to you, we need to look at exactly how an underwriter thinks. These financial professionals are not bad people trying to ruin your dreams of owning property.
They are simply risk assessors who act like private detectives for the bank. Their main job is to make sure you can actually afford the monthly payments without going bankrupt down the road.
Most people only focus on their credit score and their total income before applying. However, the approval process goes so much deeper than those two basic numbers.
The Mystery of the Unexplained Bank Deposits
One of the biggest things people ignore is how they move their cash around before applying for a loan. You might think that having extra money in your checking account is a massive bonus.
In reality, a sudden appearance of cash is a massive red flag for any loan officer. Underwriters call this "unsourced funds," and it makes them incredibly nervous about your financial stability.
They want to know exactly where every single dollar came from over the last two months. If you suddenly deposit a large chunk of money, they will assume you secretly borrowed it from a friend.
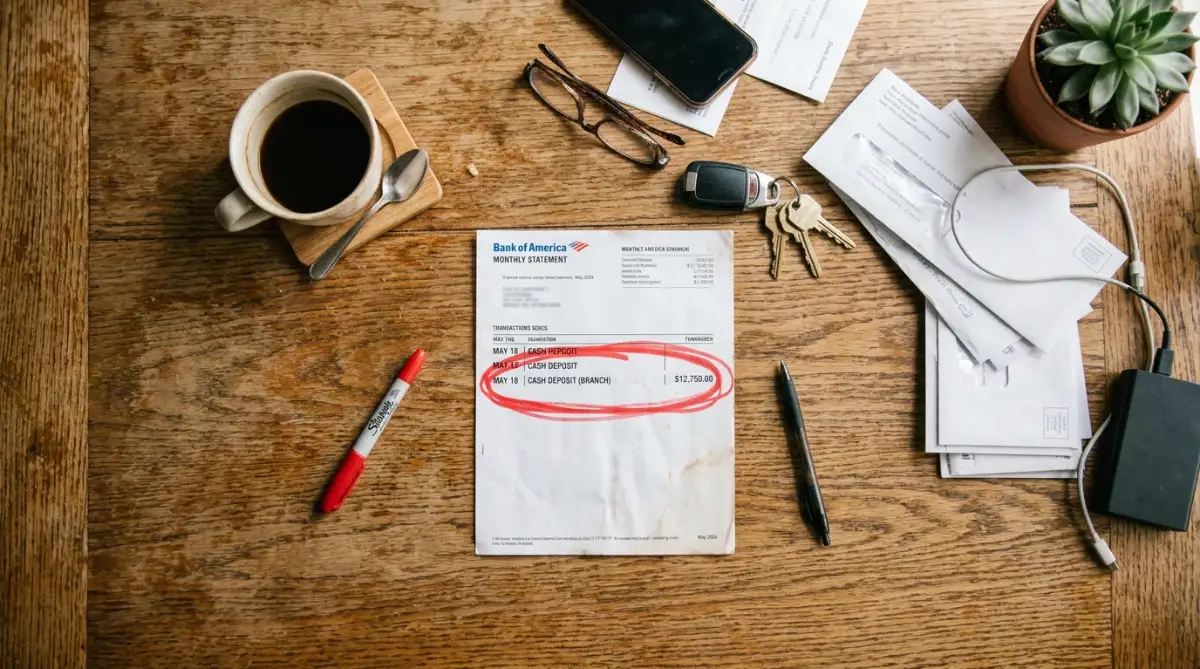
Are you ready to see exactly what they look for? Check out this quick breakdown from a former loan officer who explains the hidden paper trail.
Imagine you sold your old car for cash and put that money straight into your savings account. To you, that is simply being responsible and adding to your future house fund.
To the underwriter, it looks like an undisclosed personal loan that you now have to pay back. If you cannot prove exactly where that money came from with a solid paper trail, they will completely exclude it from your application.
Always keep copies of bills of sale, copies of cleared checks, and detailed receipts for anything you sell. If your parents give you money as a gift for the house, they will need to sign an official gift letter.
Quick Checklist: The "Acceptable Paper Trail" for Extra Cash
Before you deposit any unusual amount into your account, make sure you have:
- A signed Bill of Sale (if you sold a car, boat, or valuable item).
- A copy of the cleared check from the buyer.
- A signed and dated Gift Letter (if the money is from family).
- A clear bank receipt showing the exact matching deposit amount.
The Hidden Ghost Debts You Forgot About
Another massive issue that catches buyers off guard is the concept of hidden financial obligations. You might pull your own credit report and see that your credit cards and car loans are fully paid off.
But underwriters look for things that do not always show up immediately on a basic consumer credit check. Have you ever co-signed an auto loan for a younger sibling or a close friend?
Even if you have never made a single payment on that car, that debt belongs to you in the eyes of the bank. This is known as a contingent liability.
It means that if your friend stops paying, the bank will absolutely come after you for the money. The underwriter will calculate that entire monthly payment against your personal income.
I actually almost lost my own loan approval because I co-signed an apartment lease for my cousin a year prior. I had completely forgotten about it, but the underwriter found it on a deep public records search and immediately halted my file.
The Illusion of a Perfectly Stable Job
We all know that you need a job to get a house, but how you get paid matters just as much as how much you make. Many applicants think that getting a massive promotion right before buying a house is a great idea.
However, changing how your income is structured can completely derail your entire application. Let us say you transition from a flat salaried position to a heavily commission-based sales role.
Even if your new job pays twice as much money, the underwriter cannot easily predict your future earnings. They usually require a long history of commission-based income to feel safe approving you.
They want consistency above almost everything else in your file. A sudden shift from W2 employment to independent contractor status is even worse for your current application.
Myth vs Reality: Pulling Your Credit Too Often
Myth: Checking your own credit score will automatically drop your score and make the bank deny you.
Reality: When you check your own score, it is considered a soft pull and does absolutely no damage. The real danger comes from hard inquiries made by other lenders right before closing.
Underwriters do a final credit check just days before you get the keys to your new home. If they see that you recently applied for a new credit card to buy furniture, your file will immediately be flagged.
They assume you are taking on new debt because you are short on cash for the house. Never apply for new store cards, auto loans, or even personal loans until you have officially moved in.
The Secret Danger of Subscription Overload
When an underwriter asks for your bank statements, they are not just looking at your total balance. They read through every single line item to see exactly how you spend your cash on a daily basis.
They are looking for undisclosed obligations that might eat up your monthly budget. If they see a consistent monthly payment to a strange company, they will ask you to explain it.
Sometimes, this could be an undisclosed payment plan for expensive dental work or an old tax repayment agreement. Even high monthly payments to heavily expensive subscription services can cause them to ask uncomfortable questions.
They want to ensure your lifestyle does not secretly cost more than your documented income can support. If you are paying off a private debt to a family member via regular mobile transfers, they will find out.
What You Think is Fine vs. What The Underwriter Sees
| Your Daily Habit | How the Bank Reads It |
| :--- | :--- |
| Transferring $500 to a friend every month | Possible hidden loan repayment. |
| A $100/month random software subscription | Undisclosed debt or payment plan. |
| Keeping a $5 balance in checking | High risk of future overdrafts. |
Employment Gaps and the Explanations They Demand
Life happens, and sometimes people take time off work to care for a sick relative or travel. While a gap in your resume might not bother a future boss, it certainly bothers a mortgage underwriter.
If you have been unemployed for more than a month in the recent past, be prepared to explain exactly why. They want to see a letter of explanation written by you, detailing the specific reasons for your break in employment.
They are trying to figure out if you have a habit of quitting jobs impulsively. If you work in an industry with seasonal layoffs, like construction, they need to see a historical pattern of you returning to work.
The longer your gap in employment, the harder it becomes to prove that your current income is completely stable. Always be completely honest about these gaps upfront rather than hoping they simply miss it.
The Truth About Debt-to-Income Nuances
Your Debt-to-Income (DTI) ratio is the holy grail of your entire mortgage application file. It is the simple math of how much money goes out versus how much comes in every month.
But what people overlook is exactly what the bank includes in the "debt" category. They do not care about your monthly grocery bill, your electricity bill, or your cell phone plan.
They care deeply about minimum credit card payments, student loans, and child support obligations. Even if your student loans are currently deferred and you are not making payments, they still count against you.
The underwriter will take a percentage of your total student loan balance and pretend that is your monthly payment. This hidden calculation alone is enough to push a perfectly good buyer over the allowed debt limit.
If you pay child support or alimony, that must be fully disclosed from the very beginning. Hiding court-ordered payments is considered mortgage fraud and will result in an instant, non-negotiable denial.
Overdrafts: The Ultimate Sign of Financial Stress
Think about your primary checking account over the last sixty days. Have you ever let your balance drop below zero, even for just a few hours before getting paid?
To you, an overdraft fee might just be a minor annoyance or a small banking mistake. To an underwriter, an overdraft is a glaring sign that you live paycheck to paycheck and struggle to manage funds.
If they see multiple overdraft fees or non-sufficient funds (NSF) charges on your statements, they will panic. It tells them that adding a massive housing payment to your life is a terrible idea.
Before you ever apply for a home loan, you need to keep your checking account squeaky clean. Set up low-balance alerts on your phone so you never accidentally overdraw your account at the grocery store.
Undisclosed Real Estate and Timeshare Nightmares
You might think that keeping quiet about a small piece of land you own is a smart move. Some buyers fail to mention timeshares because they do not view them as traditional real estate.
However, if you owe monthly maintenance fees or property taxes on any other asset, the underwriter must know. They run comprehensive property searches using your name and social security number across the entire country.
If they discover a hidden timeshare or a vacant lot in another state, they will recalculate your entire application. Those extra yearly taxes and association fees will be added to your current debt ratio.
It is always better to over-communicate with your loan officer than to have the underwriter catch you in a lie. Transparency is the only way to navigate this complicated process without losing your mind.
The Final Verification of Employment (VOE)
Many buyers celebrate the moment they get their initial loan approval letter from the bank. They think the hard part is over and they can finally relax and pack their boxes.
But underwriters perform a sneaky final check known as the verbal verification of employment. Usually, on the exact day of your closing, they will call your boss directly.
They simply want to ask one question: "Does this person still work here today?" If you got angry and quit your job the day before closing, the bank will pull the funds immediately.
Never put in your two weeks' notice or change employment status until the keys are physically in your hand. The underwriter's job is not over until the money is officially transferred to the seller.
Pro-Level Strategies to Make Your Loan Officer Smile
Taking control of your home buying journey means thinking exactly like the person reviewing your file. You want to present an application so clean and organized that they have absolutely no reason to doubt you.
The easiest way to do this is by becoming a master of your own financial paper trail. You need to gather every single document before they even ask for it.
When you hand over a perfectly organized folder, you immediately build trust with your lender. Let us look at a few smart ways to prepare your money for the ultimate test.
The Magic of Seasoning Your Money
Underwriters use a specific industry term called "seasoned funds" when looking at your bank statements. This simply means that the money you plan to use for your down payment has been sitting in your account for a while.
Usually, they want to see that cash resting peacefully in your bank for at least sixty full days. If the money has been there for two complete statement cycles, they stop asking questions about where it came from.
If you are planning to sell a motorcycle or cash out some investments, do it several months before applying. This gives your money enough time to age properly in your checking account.
By the time the bank asks for your two most recent statements, those large deposits are basically ancient history. This completely eliminates the need for you to write long letters explaining your cash sources.
Understanding this timeline is just as important as knowing exactly how mortgage rates work before you lock in a contract. Timing is everything when dealing with massive financial decisions.
Mastering the Art of the Gift Letter
Many first-time buyers get a little bit of help from their parents or close relatives. Getting a financial gift for a down payment is completely fine, but there is a very strict rulebook to follow.
You cannot just have your dad wire ten thousand dollars into your account on a Tuesday. The bank will immediately flag that as a massive secret loan that requires monthly payments.
Instead, you need a highly specific document called a gift letter, signed by the person giving you the cash. This letter legally states that the money is a pure gift and no repayment is expected ever.
According to guidelines provided by the Department of Housing and Urban Development, gift funds must be strictly documented to prevent loan fraud. The underwriter will likely even ask to see your parents' bank statements to prove they actually had the money to give.
I know this feels extremely invasive, but warning your family ahead of time makes the process much smoother. Just tell them that the bank acts like a strict detective and needs proof for every penny.
Writing a Bulletproof Letter of Explanation
No one has a perfectly flawless financial history, and underwriters honestly expect to see a few bumps in the road. You might have a random late payment from a few years ago or a short gap between jobs.
Whenever they spot a red flag, they will ask you to provide a Letter of Explanation (LOE). Do not write a massive, emotional essay detailing every sad thing that happened to you.
They do not want a long story; they just want basic facts and proof that the issue is permanently fixed. Keep your sentences short, entirely factual, and totally direct.
If you missed a payment because you were in the hospital, simply state the dates you were hospitalized. Attach a copy of your medical discharge paper and clearly state that you are fully recovered and working again.
Pro Tip from the Trenches: I once wrote a five-page letter defending a late credit card payment, thinking my sad story would earn their sympathy. My loan officer immediately sent it back and told me to shrink it to three sentences. I quickly learned that underwriters only care about raw facts, not personal feelings or excuses.
Getting Ahead of the Human Resources Delay
We already talked about how the bank will verify your employment multiple times. What most buyers forget is that your company's HR department might be incredibly slow to respond.
If you work for a massive corporation, it can take days for an HR rep to return a phone call. This simple delay can actually push your closing date back and cause massive stress.
Go talk to your boss or your HR manager the moment you start looking for houses. Let them know that a bank will be calling to verify your job status soon.
Ask them for a direct phone number or a specific email address that the underwriter can use. Being proactive about this communication chain removes a massive hurdle on closing week.
Heartbreaking Errors That Destroy Final Approvals
It is incredibly painful to watch someone lose their dream home just days before getting the keys. The saddest part is that these denials usually happen because of entirely preventable mistakes.
People tend to relax the moment they get their initial pre-approval letter. They start making everyday financial choices without realizing they are completely sabotaging their own file.
Let us walk through the most dangerous traps that consistently ruin good applications. If you avoid these specific actions, your path to homeownership will remain perfectly safe.
The Furniture Store Trap
This is easily the most common way good buyers destroy their own loans. You finally have a house under contract, and you want to start measuring rooms for new couches and beds.
You walk into a local furniture store, and the salesman offers you zero percent financing for two whole years. It sounds like an amazing deal, so you let them swipe your information to open a new store account.
That single credit check will instantly send an alert straight to your mortgage underwriter. Even worse, the new monthly payment for that furniture changes your entire debt-to-income math.
Suddenly, your monthly obligations are too high, and your mortgage is instantly denied. You now have a beautiful new living room set but absolutely no living room to put it in.
Never open new credit accounts, and completely avoid managing unsecured loans without credit damage during this waiting period. Do not buy a fridge, a car, or even a fancy new television on credit until after you move in.
The Paradox of Paying Off Old Collections
It sounds completely backwards, but trying to be responsible can sometimes hurt your loan application. Imagine you pull your credit report and notice an old, forgotten medical bill in collections from years ago.
Your first instinct is probably to call that debt collector and pay it off immediately to look good for the bank. However, paying off an ancient collection account actually updates the "Date of Last Activity" on your credit file.
The credit bureaus see this sudden activity and temporarily drop your credit score. That sudden drop might be just enough to disqualify you from the housing program you applied for.
Experts at the Consumer Financial Protection Bureau often warn buyers not to make sudden moves without consulting their loan officer first. If the underwriter wants you to pay off a collection account, they will explicitly tell you to do so.
Until they give you that direct instruction, leave your old debts completely alone. Sometimes, they prefer you just leave sleeping dogs lie rather than stirring up old negative marks.
The Danger of Secret Debt Consolidation
The stress of buying a house often makes people want to clean up their entire financial life at once. You might think taking out a new loan to merge all your credit cards together is a brilliant move.
While this sounds smart on paper, the timing is absolutely terrible. If you start changing how your debts are structured, the underwriter has to start their math completely over.
They have to re-verify the new loan terms and check how it impacts your daily budget. This directly ties into the many common myths about debt consolidation that confuse everyday buyers.
Just keep making your normal minimum payments while your housing file is open. Save your grand financial restructuring plans for a few months after you unpack your boxes.
The Co-Signing Nightmare You Cannot Escape
We touched on this earlier, but the gravity of co-signing cannot be overstated. You might get a frantic call from a family member begging you to help them secure a student loan.
You know they are responsible, so you quietly add your name to their application to help them out. The moment you do this, their new massive debt becomes your permanent legal responsibility.
The bank does not care if your nephew promises to make every single payment on time. The underwriter will assume you are paying for it out of your own pocket.
You must carefully read this before you endorse a student loan for anyone, especially while house hunting. Protecting your own borrowing power has to be your absolute main priority right now.
Moving Large Sums Blindly Between Accounts
Modern banking apps make it incredibly easy to slide money between your savings and checking accounts with one swipe. While this is super convenient, it creates a massive headache for the person verifying your assets.
If you constantly transfer a thousand dollars back and forth every week, your statements become a chaotic mess. The underwriter has to track every single movement to make sure you are not borrowing hidden money.
They will make you print out statements for every account involved and highlight matching transactions. It turns a simple asset check into a frustrating, tedious audit of your daily life.
Pick one single bank account to hold your house funds and leave it completely alone. Stop treating your savings account like a revolving door for your weekend expenses.
Ignoring the Realities of Unsecured Borrowing
Sometimes buyers panic when they realize they are slightly short on cash for closing costs. Out of desperation, they might try to grab a fast cash advance or a sketchy online loan.
This is the exact same reason why reasons your personal loan gets rejected usually overlap with mortgage denials. These fast lenders report to credit bureaus rapidly, and the bank will catch you almost instantly.
Even if you explore options to pledge collateral for a secured borrowing option, it still adds a new liability.
If you are honestly short on cash, tell your real estate agent immediately. They might be able to negotiate with the seller to cover some of your closing costs legally.
Your Ultimate Action Plan for Closing Day
Navigating the hidden maze of loan approval does not have to be a terrifying experience. Once you understand the basic rules of the game, you can completely protect yourself from sudden heartbreak.
The secret is to keep your financial life incredibly boring and entirely predictable until the deal is done. Pay your regular bills on time, keep your money sitting quietly in the bank, and avoid any major lifestyle changes.
If you ever feel tempted to make a big purchase or move money around, call your loan officer first. They are your best advocate and will happily tell you if a specific action will hurt your file.
By staying transparent and heavily organized, you make the underwriter's job incredibly easy. An easy file gets approved much faster, bringing you one step closer to holding those front door keys.
You truly have the power to control your own destiny in this massive financial transaction. Treat your bank accounts like a quiet museum exhibit where nothing can be touched or moved without permission.
Answers to Your Biggest Underwriting Worries
How long does an underwriter actually take to review a file?
Normally, a clean file takes anywhere from three to eight business days to get a solid answer. If they find confusing bank deposits or missing tax forms, it can easily stretch into a few weeks. Being highly organized upfront is the absolute best way to speed up this waiting game.
Can an underwriter deny my loan after it was already pre-approved?
Yes, this happens very frequently if your financial situation changes between the pre-approval and the final closing day. If you lose your job, take on heavy new debt, or drain your savings, they will immediately revoke the offer. A pre-approval is just an educated guess, while the final underwriting check is the actual legal commitment.
Will checking my credit score online ruin my mortgage application?
Checking your own score using standard consumer apps is a soft pull and never hurts your rating. The real danger comes from applying for new credit cards or trying to finance a car right before closing. To stay safe, simply monitor your own numbers without ever filling out new loan applications.
What happens if I cannot explain a random large cash deposit?
If you absolutely cannot prove where a large chunk of money came from, the bank will not let you use it. They will essentially pretend that cash does not exist when calculating your total available assets. If removing that money leaves you short on your down payment, your file will be paused or denied.
Do underwriters care if I pay off my car loan early?
If you want to clear a debt, you must ask your loan officer before making any sudden massive payments. Sometimes, dropping cash to clear a debt lowers your available assets too much for the bank's liking. If you find yourself wondering what to do if you can't make your car payment, always talk to your lender instead of hiding it.
Disclaimer: The information provided in this article is for educational and informational purposes only and should not be considered professional financial or legal advice. Mortgage guidelines and underwriting standards change frequently and vary heavily depending on your location and specific lender. Always consult with a licensed loan officer or certified financial advisor before making any major financial decisions regarding real estate.